


Income Tax - Calculation of Tax
Verified 15 April 2026 - Public Service / (Prime Minister)
Want to know how your income tax is calculated? Gross tax is calculated using a progressive scale. This amount is adjusted to determine the net tax payable. To calculate your tax amount, you can use the online simulator. You can also calculate the amount of your tax yourself, by proceeding in stages. We tell you what you need to know about your 2025 income (to be reported in 2026).
To calculate your tax amount, you can use the calculation simulator:
Estimate the amount of your 2025 income tax (2026 return)
You can also consult the online tax return brochure and the explanatory note to the tax return.
These documents contain a sheet for calculating the amount of tax.
Step-by-step approach
You must list your income by category and add it up, including:
- Taxable salary
- Pensions, retired
- Benefits: industrial and commercial (BIC) non-commercial (BNC) or agricultural (BA)
- Land income
- Movable income and capital gains on securities
- Real estate capital gains.
Warning
We have to apply some abatements on such income, in particular business expenses.
Example :
A single person has no income other than his salary and declares €30,000 net taxable salary.
If he chooses the flat-rate deduction of professional expenses of 10%, its overall gross income will be:
€30,000 - (€30,000 x 10%) = €27,000.
Overall net income = gross total income - deductible expenses
Deductible expenses include:
Taxable net income = overall net income - special allowances
You can benefit from a abatement special if you are in any of the following situations:
Répondez aux questions successives et les réponses s’afficheront automatiquement
You are 65 years of age or older
You must have 65 years of age or older as at 31 december 2025:
- If your income is less than €17,670, you are entitled to a €2,822.
- If your income is between €17,670 and €28,430, you are entitled to a €1,411.
This allowance can be doubled if 2 members of the household meet the age requirement.
This abatement cannot be stacked with the special allowance for the disabled.
You are invalid
If you are disabled, you can benefit from the following benefits:
- If your income is less than €17,670, you are entitled to a €2,822.
- If your income is between €17,670 and €28,430, you are entitled to a €1,411.
This allowance can be doubled if 2 members of the household meet the age requirement.
This abatement cannot be stacked with the special allowance for persons aged 65 or over.
You are affected if you have any of the following benefits:
- Military disability pension for a disability of at least 40%
- Disability pension for accident at work of at least 40%
- Mobility inclusion card marked « invalidity ».
You are bringing your child, whether married, entered into a civil partnership or responsible for the family
You benefit from a rebate of €6,855 if you attach to your tax home :
- Your child who is married or entered into a civil partnership, with or without children
- Or your child in charge of family.
Your child (or their spouse or Civil partnership partner) must:
- Under 21 years of age
- Be under 25 years of age if studying
- Be disabled (mobility card included with "invalidity" or invalidity card of at least 80%), regardless of age.
Please note
If you pay child support to your adult child, rules are different.
The determination of the gross tax takes place in several successive stages.
1Determine the number of tax shares
The number of shares you are entitled to depends on your situation:
It also takes into account your dependants:
2Calculate the family quotient
Family Quotient = net taxable income / number of tax units of the household
Example :
A couple is entitled to 2 shares.
If its net taxable income is €30,000, its family quotient is: €30,000 / 2 = €15,000.
3Apply the scale
The scale is applied to the family quotient obtained.
This scale comprises several bands.
Income bands | Tax rate of income bracket |
|---|---|
Up to €11,600 | 0% |
From €11,601 à €29,579 | 11% |
From €29,580 à €84,577 | 30% |
From €84,578 à €181,917 | 41% |
More than €181,917 | 45% |
The marginal tax rate (TMI) is the tax rate that applies to the highest slice of your income.
The average tax rate is the average rate at which your income is taxed. It tells you the share of your income tax.
Please note
The tax benefit for children is limited. It's the family quotient cap.
Here are some examples of calculations:
Répondez aux questions successives et les réponses s’afficheront automatiquement
For a bachelor
One single (single unit household) with a net taxable income of €30,000, without any reduction or deduction.
His family quotient is €30,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €29,579 : (€29,579 - €11,600) × 11% = €17,979 × 11% = €1,977.69
- From €29,580 à €30,000 : (€30,000 - €29,579) x 30% = €421 × 30% = €126.30.
Its gross tax is: €0 + €1,977.69 + €126.30 = €2,103.99.
The marginal tax rate (MIR) of this taxpayer is 30%, because his family quotient puts him in that bracket. But not all of his income is taxed at 30%.
Its average tax rate is 7.01% (2 103.99: 30 000).
For a married or entered into a civil partnership couple without children
Net taxable income of €60,000
One married or entered into a civil partnership without children (household of 2 units) with taxable net income of €60,000.
His family quotient is €60,000 : 2 = €30,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €29,579 : (€29,579 - €11,600) × 11% = €17,979 × 11% = €1,977.69
- From €29,580 à €30,000 : (€30,000 - €29,579) x 30% = €421 × 30% = €126.30.
The gross tax of each member of the couple is: €0 + €1,977.69 + €126.30 = €2,103.99.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 2, since it is a married or entered into a civil partnership couple.
The couple will therefore have to pay a tax of €2,103.99 × 2, or €4,207.98.
The marginal tax rate (MTR) of this couple is 30%, because his family quotient puts him in that bracket. But not all of his income is taxed at 30%.
Its average tax rate is 7.01% (4 207,98: 60 000).
Net taxable income of €90,000
One married or entered into a civil partnership without children (household of 2 units) with taxable net income of €90,000.
His family quotient is €90,000 : 2 = €45,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €29,579 : (€29,579 - €11,600) × 11% = €17,979 × 11% = €1,977.69
- From €29,580 à €45,000 : (€45,000 - €29,579) x 30% = €15,421 × 30% = €4,626.30.
The gross tax of each member of the couple is: €0 + €1,977.69 + €4,626.30 = €6,603.99.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 2 since it is a married or entered into a civil partnership couple.
The couple will therefore have to pay a tax of €6,603.99 × 2, or €13,207.98.
The marginal tax rate (MTR) of this couple is 30%, because his family quotient puts him in that bracket. But not all of his income is taxed at 30%.
Its average tax rate is 14.67% (13 207.98: 90 000).
For a married or entered into a civil partnership couple with 1 child
Net taxable income of €60,000
One married or entered into a civil partnership couple with 1 child (focus of 2.5 shares, 1 share for each parent and 1 half share for the child) with taxable net income of €60,000.
His family quotient is €60,000 : 2.5 = €24,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €24,000 : (€24,000 - €11,600) x 11% = €12,400 × 11% = €1,364.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 2.5 since it is a married or entered into a civil partnership couple with 1 child.
The couple with 1 child should therefore pay a tax of: €1,364 x 2.5, or €3,410.
The couple is entitled to a maximum tax benefit of €1,807 for his child (this is the family quotient cap).
As a reminder, a married or entered into a civil partnership couple without children who received a net taxable income of €60,000 shall pay a tax of €4,207.98.
Thus, the advantage linked to the child is €797.98 (€4,207.98 - €3,410).
The amount of this benefit is less than the maximum benefit of €1,807.
The couple with 1 child will therefore owe a tax of €3,410.
The marginal tax rate (MTR) of this couple with 1 child is 11%, because his family quotient puts him in that bracket. But not all of his income is taxed at 11%.
Its average tax rate is 5.68% (3 410: 60 000).
Net taxable income of €90,000
One married or entered into a civil partnership couple with 1 child (focus of 2.5 shares, 1 share for each parent and 1 half share for the child) with taxable net income of €90,000.
His family quotient is €90,000 : 2.5 = €36,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €29,579 : (€29,579 - €11,600) × 11% = €17,979 × 11% = €1,977.69
- From €29,580 à €36,000 : (€36,000 - €29,579) x 30% = €6,421 × 30% = €1,926.30.
The gross tax of each member of the couple is: €0 + €1,977.69 + €1,929.30 = €3,903.99.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 2.5 since it is a married or entered into a civil partnership couple with 1 child.
The couple with 1 child should therefore pay a tax of €3,903.99 × 2.5, or €9,759.97.
The couple is entitled to a maximum tax benefit of €1,807 for his child (this is the family quotient cap).
As a reminder, a married or entered into a civil partnership couple without children who received a net taxable income of €90,000 shall pay a tax of €13,207.98.
Thus, the advantage linked to the child is €3,448.01 (€13,207.98 - €9,759.97).
This amount exceeds the maximum tax benefit to which the couple is entitled for their child €1,641.01 (€3,448.01 - €1,807).
The couple with 1 child will therefore owe a tax of €11,400.98 (€9,759.97 + €1,641.01).
The marginal tax rate (MTR) of this couple with 1 child is 30%, because his family quotient puts him in that bracket. But not all of his income is taxed at 30%.
Its average tax rate is 12.67% (11 400.98: 90 000).
For a married or entered into a civil partnership couple with 2 children
Net taxable income of €60,000
One married or entered into a civil partnership couple with 2 children (focus of 3 shares, 1 share for each parent and 1 half share for each child) having received a net taxable income of €60,000.
His family quotient is €60,000 : 3 = €20,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €20,000 : (€20,000 - €11,600) x 11% = €8,400 × 11% = €924.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 3 since it is a married or entered into a civil partnership couple with 2 children.
The couple with 2 children should therefore pay a tax of: €924 x 3, or €2,772.
The couple is entitled to a maximum tax benefit of €3,614 (€1,807 x 2) for his 2 children (this is the family quotient cap).
As a reminder, a married or entered into a civil partnership couple without children who received a net taxable income of €60,000 shall pay a tax of €4,207.98.
Thus, the advantage related to the 2 children is €1,435.98 (€4,207.98 - €2,772).
The amount of this benefit is less than the maximum benefit of €3,614.
The couple with 2 children will therefore owe a tax of €2,772.
The marginal tax rate (MTR) of this couple with 2 children is 11%, because his family quotient puts him in that bracket. But not all of his income is taxed at 11%.
Its average tax rate is 4.62% (2 772: 60 000).
Net taxable income of €90,000
One married or entered into a civil partnership couple with 2 children (focus of 3 shares, 1 share for each parent and 1 half share for each child) having received a net taxable income of €90,000.
His family quotient is €90,000 : 3 = €30,000.
For the calculation of his tax:
- Up to €11,600 : 0%
- From €11,601 à €29,579 : (€29,579 - €11,600) × 11% = €17,979 × 11% = €1,977.69
- From €29,580 à €30,000 : (€30,000 - €29,579) x 30% = €421 × 30% = €126.30.
The gross tax of each member of the couple is: €0 + €1,977.69 + €126.30 = €2,103.99.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 3 since it is a married or entered into a civil partnership couple with 2 children.
The couple with 2 children should therefore pay a tax of €2,103.99 × 3, or €6,311.97.
The couple is entitled to a maximum tax benefit of €3,614 (€1,807 x 2) for his 2 children (this is the family quotient cap).
As a reminder, a married or entered into a civil partnership couple without children who received a net taxable income of €90,000 shall pay a tax of €13,207.98.
Thus, the advantage related to children is €6,896.01 ( €13,207.98 - €6,311.97).
This amount exceeds the maximum tax benefit to which the couple is entitled for their two children €3,282.01 (€6,896.01 - €3,614).
The couple with 2 children will therefore owe a tax of €9,593.98 (€6,311.97 + €3,282.01).
The marginal tax rate (MTR) of this couple with 2 children is 30%, because his family quotient puts him in that bracket. But not all of his income is taxed at 30%.
Its average tax rate is 10.66% (9 593.98: 90 000).
For a single parent with 1 child
One single parent with 1 child (2-share household, 1 share for the parent, 1 half-share for the child in principal residence and 1 additional half-share as a single parent) having received a net taxable income of €30,000.
His family quotient is €30,000 : 2 = €15,000.
- Up to €11,600 : 0%
- From €11,601 à €15,000 : (€15,000 - €11,600) x 11% = €3,400 x 11% = €374.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 2 since it is a single parent with 1 child.
To note : the tax benefit is reduced by half in the case of alternating residence.
The gross family tax is: €374 x 2, or €748.
A single parent with 1 child is entitled to a maximum tax benefit of €4,262 for his child (this is the family quotient cap).
As a reminder, a single person without children who received a net taxable income of €30,000 shall pay a tax of €2,103.99.
Thus, the advantage linked to the child is €1,355.99 (€2,103.99 - €748).
The amount of this benefit is less than the maximum benefit of €4,262.
The single parent with 1 child will therefore have to pay a tax of €748.
The marginal tax rate (MTR) of this family is 11%, because his family quotient puts him in that bracket. But not all of his income is taxed at 11%.
Its average tax rate is 2.49% (748: 30,000).
For a single parent with 2 children
One single parent with 2 children (2.5-share household, 1 share for the parent, 1 half-share for each child in a principal residence and 1 additional half-share as a single parent) who received a net taxable income of €30,000.
His family quotient is €30,000 : 2.5 = €12,000.
- Up to €11,600 : 0%
- From €11,601 à €12,000 : (€12,000 - €11,600) x 11% = €400 x 11% = €44.
This tax must be multiplied by the number of shares in the tax household. In this example, it will be multiplied by 2.5 since it is a single parent with 2 children.
To note : the tax benefit is reduced by half in the case of alternating residence.
The gross family tax is: €44 x 2.5, or €110.
A single parent with 2 children is entitled to a maximum tax benefit of €6,069 (€4,262 + €1,807) for his 2 children (this is the family quotient cap).
As a reminder, a single person without children who received a net taxable income of €30,000 shall pay a tax of €2,103.99.
Thus, the advantage linked to the child is €1,993.99 (€2,103.99 - €110).
The amount of this benefit is less than the maximum benefit of €6,069.
The single parent with 2 children will therefore have to pay a tax of €110.
The marginal tax rate (MTR) of this family is 11%, because his family quotient puts him in that bracket. But not all of his income is taxed at 11%.
Its average tax rate is 0.36% (110: 30,000).
Infographie - Income tax: 2026 scale
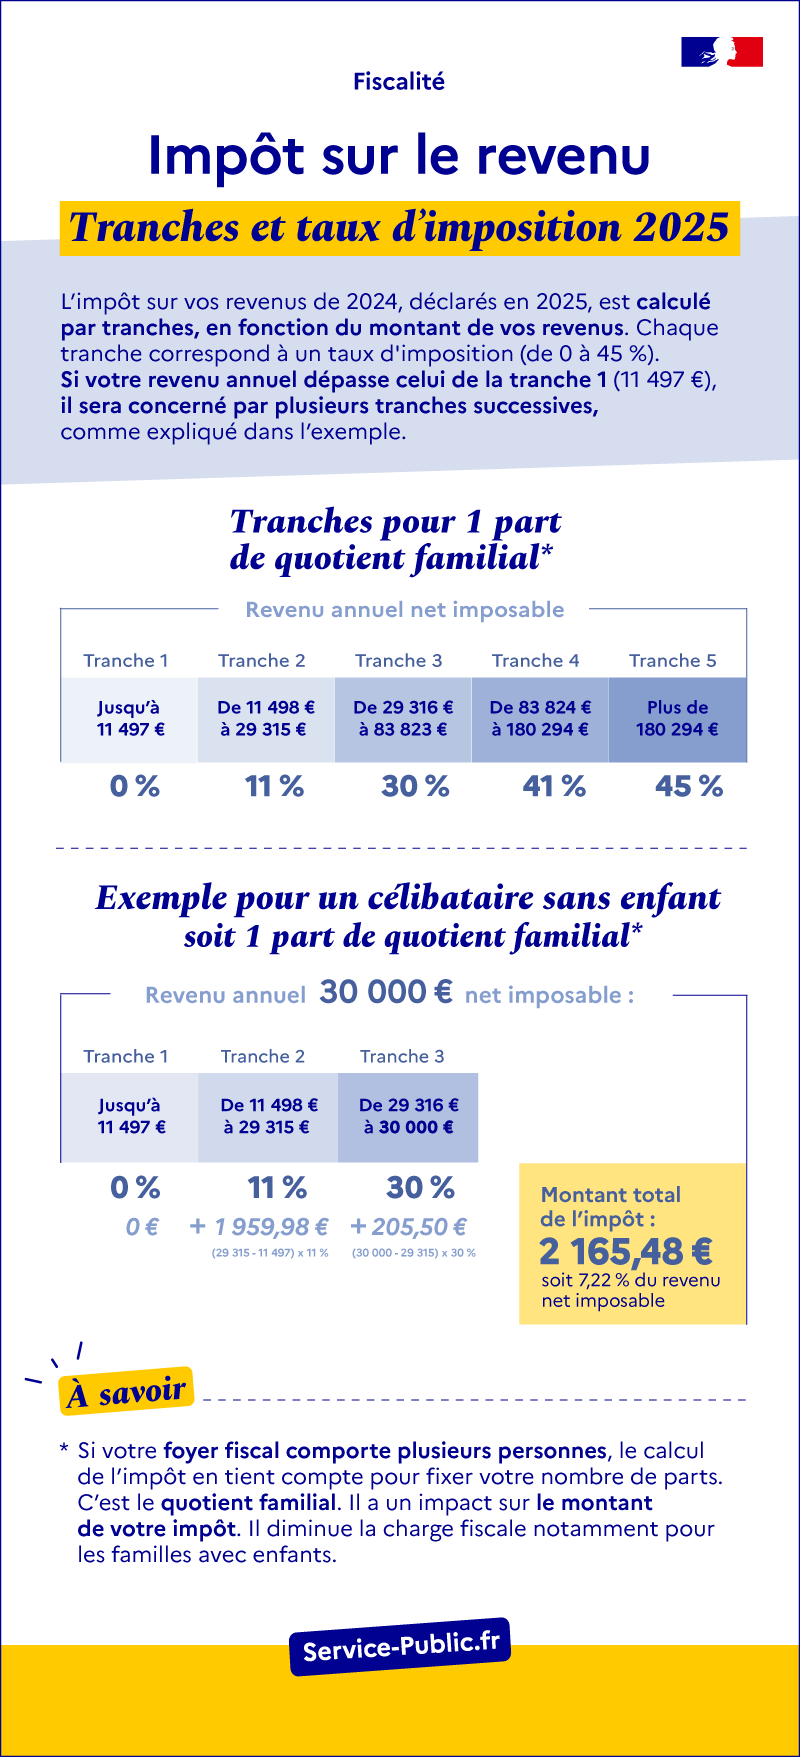
Ouvrir l’image dans une nouvelle fenêtre
Income tax
2026 tax brackets and rates
Your tax is calculated in installments, based on the amount of your income. Each bracket corresponds to a tax rate (from 0 to 45%). If your annual income exceeds that of tranche 1 (€11,600), it will be covered by several successive tranches, as explained in the example.
Slices for 1 share of family quotient:
- Up to €11,600 (tranche 1): 0% tax rate
- From €11,601 to €29,579 (tranche 2): tax rate of 11%
- From €29,580 to €84,577 (tranche 3): tax rate of 30%
- From €84,578 to €181,917 (tranche 4): tax rate of 41%
- Over €181,917 (tranche 5): 45% tax rate
Example of calculation for 1 share of family quotient:
A single person (1 share) whose annual net taxable income is € 30,000, the calculation of his tax is as follows:
- Up to €11,600 (tranche 1): €0
- From €11 601 to €29 579 (tranche 2): €1 977.69, i.e. (29 579 – 11 600) x 11%
- From €29 580 to €30 000 (tranche 3): €126.30, i.e. (30 000 – 29 579) x 30%
Total amount of tax: € 2,103.99, or 7.01% of his net taxable income.
Namely: if your tax household has several people, the tax calculation takes this into account to determine your number of shares. That's the family quotient. This mechanism has an impact on the amount of your tax. In particular, it reduces the tax burden for families with children.
Gross tax can be adjusted by certain devices, depending on your situation.
The tax authorities check whether you are affected by these arrangements and apply them one after the other, in a specific order.
1Capping the effects of the family quotient
The tax benefit provided by the additional half-share(s) to which you are entitled is capped.
It cannot exceed an amount set according to your situation.
The tax reduction linked to the family quotient is limited to €1,807 for each additional half-part (€904 for each additional quarter share).
In some specific situations, the tax reduction linked to the family quotient is different.
For example:
- €4,262 for the share granted to a single parent with 1 dependent child
- €1,079 for the part granted, subject to conditions, if you raised a child alone for 5 years
- €3,608 for the half-part granted if you are disabled or a veteran.
Beyond the limit that corresponds to your situation, the benefit granted for your additional half-share(s) is no longer taken into account in calculating the amount of your tax.
Please note
Of special rules shall apply to the calculation of the tax of taxpayers domiciled in overseas departments and regions.
2Discount
The discount is a mechanism that allows reduce your tax if you are low taxed.
The discount applies automatically, you do not have to take any action.
You can benefit from the discount if the amount of your tax does not exceed ceiling which depends on your situation:
Répondez aux questions successives et les réponses s’afficheront automatiquement
You're single
You receive a discount if the gross amount of your income tax does not exceed €1,982.
You are a couple subject to joint taxation
You get a discount if the gross amount of your income tax does not exceed €3,277.
The amount of the discount you can benefit from is calculated by the tax authorities.
It is then deducted from your gross tax.
The calculation of the discount depends on your situation:
Répondez aux questions successives et les réponses s’afficheront automatiquement
You're single
The discount is equal to the difference between €897 and 45.25% the amount of your tax.
It is deducted from your tax.
Example :
For a single person with a gross tax is €1,400 :
- The calculation of the discount is as follows: €897 - (€1,400 x 45.25%) = €897 - €633.50 = €263.50.
- The amount of tax after haircut is: €1,400 - €263.50 = €1,136.50.
You are a couple subject to joint taxation
The discount is equal to the difference between €1,483 and 45.25% the amount of your tax.
It is deducted from your tax.
Example :
For a couple with a gross tax is €2,800 :
- The calculation of the discount is as follows: €1,483 - (€2,800 x 45.25%) = €1,483 - €1,267 = €216.
- The amount of tax after haircut is €2,800 - €216 = €2,584.
3Reductions and tax credits
The tax reductions and credits to which you are entitled must be cut off the amount of your tax.
For example, the reduction for donations bodies of general interest.
FYI
The tax is not payable when the amount is less than €61. This is the amount after haircuts and tax reductions, but before any tax credits are applied.
4Exceptional contribution on high incomes
In case of high income, the exceptional contribution may be in addition to income tax.
Please note
A differential contribution on high incomes may be added. It aims to ensure a minimum tax of 20% higher incomes.
Who can help me?
Find who can answer your questions in your region
For general information
By phone:
0809,401,401
Monday to Friday from 8:30 am to 7 pm, excluding public holidays.
Free service + price call
To contact the local service managing your file
Tax department (treasury, tax department...))
Calculation of income tax
Amount below which tax is not assessed (Article 1657)
FAQ
Service Public
Ministry of Finance
Ministry of Finance